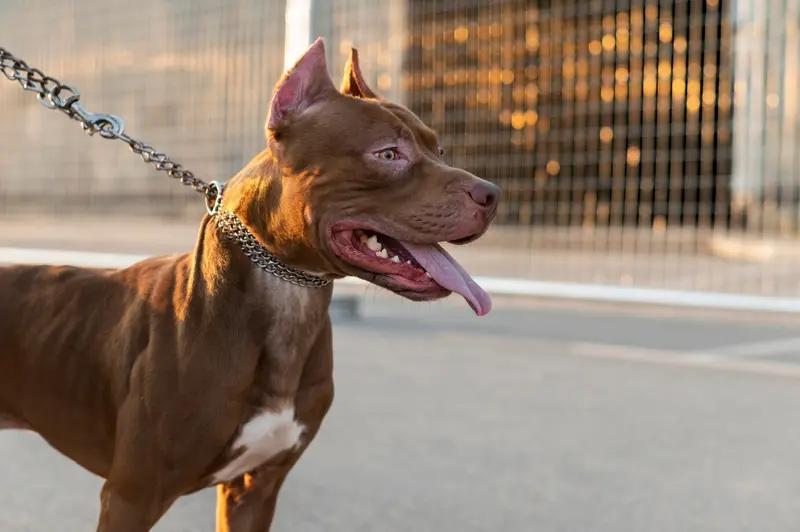
In Germany, owning a breed-specific or so-called "listed dog" (Listenhund) comes with distinct legal challenges. Often categorized under breed-specific legislation as "dangerous dogs", these breeds appear on statutory breed lists that vary from state to state. Whether you already own or plan to welcome a listed breed into your home, understanding the legal and insurance requirements is crucial. In this guide, you will find comprehensive details on liability insurance for listed dog breeds, practical tips for choosing the right policy, and real-life case studies to ensure you are fully compliant and well-protected.
What Are Listed Dog Breeds (Listenhunde)?
Listed dogs are specific breeds classified by German authorities as potentially dangerous. This classification is often based on the assumption that certain breeds carry an inherent genetic or historical risk of aggressive behavior. Among the most widely recognized listed breeds are the American Pit Bull Terrier, Staffordshire Bull Terrier, and Bullmastiff. However, canine experts widely agree that a dog's behavior depends heavily on socialization, training, and handling. As a result, blanket breed categorizations are increasingly criticized across veterinary and behavioral science communities.
Legal Regulations and Differences Across German Federal States
In Germany, breed-specific legislation varies considerably between the individual federal states (Bundesländer). While some states impose strict requirements on ownership, permits, and mandatory insurance, others take a far less restrictive approach. These differences impact everyday handling rules as well as minimum liability insurance standards. It is vital to check the specific regulations in your local municipality and state.
Specific Requirements for Dog Liability Insurance
In several federal states, taking out specialized dog liability insurance for listed breeds is mandatory by law. These policies frequently require higher minimum coverage amounts and may vary based on your dog's individual risk assessment or temperament test results. In other states, standard dog liability insurance is sufficient provided it meets baseline coverage thresholds. To stay fully compliant, always review your state's current dog legislation (Hundegesetz).
Real-Life Case Studies
Case 1: An Owner from Cologne and Her Rottweiler
An owner in Cologne decided to bring home a Rottweiler, a breed classified under Section 10 of North Rhine-Westphalia's Dog Act (LHundG NRW) as a dog of a specific breed. She applied for the necessary municipal permit in advance and secured the mandatory liability insurance meeting NRW's minimum coverage (€500,000 for personal injury, €250,000 for property damage). When an incident occurred in a park—where a passerby was startled and fell—the insurer promptly handled the personal injury and property claims. This case highlights how critical prompt compliance with local permits and proper insurance coverage is in day-to-day life.
Case 2: An Owner from Hamburg and His Bullmastiff
A dog owner in Hamburg adopted a Bullmastiff, categorized under Section 2 (3) of the Hamburg Dog Act (HundeG) as a rebuttably dangerous breed. He knew that for breeds like the American Pit Bull Terrier (under Section 2 (1) HundeG), exemptions are legally impossible because they are deemed irrefutably dangerous—making ownership banned by default and permitted only under exceptional legal interest. For his Bullmastiff, he submitted proof of the required liability insurance and successfully passed the obedience and temperament test (Wesenstest), granting him an exemption from certain handling restrictions.
Practical Tools and Actionable Advice
📋 Checklist: State-Specific Regulations for Listed Dogs (Print or Save)
- Review the breed list (Rasseliste) in your federal state.
- Check mandatory minimum liability coverage limits.
- Confirm additional mandates such as leash and muzzle requirements.
- Schedule a temperament test (Wesenstest) if required or eligible for exemptions.
- Maintain thorough documentation of training and handling records.
🔍 Step-by-Step Guide to Choosing Dog Liability Insurance
- Identify insurers that underwrite listed dog breeds in your state.
- Compare coverage limits, exclusions, and deductibles.
- Inquire about premium discounts for passing an official temperament test.
- Review verified customer feedback and claim handling track records.
- Finalize your policy and keep all documentation accessible for municipal checks.
Breed Predisposition vs. Training and Ownership
While breed-specific legislation labels certain dogs as potentially dangerous, daily reality consistently shows that environment, socialization, and training play the decisive role. A dedicated, responsible handler who properly socializes their dog and establishes clear boundaries can dramatically reduce behavioral risks. Investing in professional, force-free dog training and meeting your dog's species-appropriate needs is the single most effective way to foster a balanced companion.
Summary: Listed Breeds and Liability Insurance
Keeping a listed dog breed in Germany requires diligent planning and clear awareness of legal obligations. Adequate dog liability insurance is not only legally required in many jurisdictions—it protects you and your pet from devastating financial claims. By staying informed about your local state laws, choosing comprehensive coverage, and prioritizing structured training, you help ensure public safety and dismantle stereotypes surrounding these breeds.
Frequently Asked Questions (FAQ)
Which liability insurance do I need for a listed dog in Bavaria?
Requirements vary across federal states. Bavaria does not have a standalone "dog law"; regulations are governed by the State Penal and Regulatory Offences Act (LStVG, particularly Art. 37) and the Bavarian Ordinance on Dogs with Heightened Aggressiveness and Danger. Proof of adequate liability insurance must be submitted during the permit process or when applying for a certificate of negative assessment (Negativzeugnis). Speak with specialized insurance providers for detailed coverage criteria.
What minimum coverage amount do I need for a listed breed?
There is no uniform nationwide minimum coverage amount in Germany. Requirements depend on state-level legislation. For example, North Rhine-Westphalia mandates at least €500,000 for personal injury and €250,000 for property and financial losses, while Hamburg requires a blanket minimum of €1,000,000. Consumer advocacy groups generally recommend broad liability coverage of at least €5 million to ensure complete protection against severe claims.
Which dog breeds are classified as listed dogs in Germany?
Breed lists differ by state. Breeds such as the American Pit Bull Terrier, Staffordshire Bull Terrier, American Staffordshire Terrier, and Rottweiler frequently appear on statutory lists, but classifications vary. Always review your local municipal or state regulations to see the exact current tier list.
Do I need specialized dog liability insurance for a listed dog?
In several states, a specific liability policy acknowledging the breed's statutory status is legally mandatory. In others, standard dog liability insurance suffices as long as the provider covers listed breeds and meets state minimum coverage amounts. Always verify whether the insurer explicitly covers your dog's breed.
How much does liability insurance for a listed breed cost?
Premiums for listed dogs are typically higher than for non-listed breeds, influenced by breed classification, location, coverage sums, and policy deductibles. Comparing quotes across multiple specialized providers helps secure balanced, cost-effective coverage, though costs remain noticeably above standard policies.
What benefits does specialized liability insurance offer for listed breeds?
Dedicated policies prevent claim denials tied to breed restrictions. They often provide higher coverage amounts, legal defense support against unjustified third-party claims, and coverage terms adapted specifically to handling requirements imposed by local authorities.
Can I register my listed dog without liability insurance?
No. In most German municipalities and federal states, proof of valid liability insurance is an explicit prerequisite for registering a listed dog with the regulatory office (Ordnungsamt). Attempting to keep a listed breed without proper registration and insurance can lead to heavy administrative fines and confiscation of the dog.
What happens if my listed dog causes damage and I have insufficient insurance?
Under German civil law (§ 833 BGB), dog owners face strict liability. If your dog causes injury or property damage without adequate insurance, you are personally liable with your current and future assets. Given the potential scale of personal injury claims, carrying comprehensive liability coverage is essential.
Sources and Legal References
- Dog Act for the State of North Rhine-Westphalia (Landeshundegesetz – LHundG NRW)
- Hamburg Act on the Keeping and Handling of Dogs (HundeG Hamburg)
- Bavarian State Penal and Regulatory Offences Act (LStVG) and the Bavarian Ordinance on Dogs with Heightened Aggressiveness and Danger
- Federal and state provisions regarding mandatory dog liability insurance and statutory minimum coverage amounts